
Why Board Risk Oversight Disclosure Matters
One of the most widespread and rapidly developing risks is artificial intelligence. According to institutional investors representing $55 trillion in assets under management, investors want to understand how AI is governed, how the board is developing sufficient fluency, and how directors oversee both opportunity and risk. They want company-specific explanations identifying the AI issues that matter to the business. They want insight into the quality and frequency of information and engagement supporting oversight, and connect those responsibilities to director experience, education, and access to experts.1
Those concerns and information needs are equally applicable to cybersecurity, human capital, geopolitical exposure, regulatory change, supply-chain resilience, and other significant risks and opportunities. The subject will vary, but the disclosure challenge is the same: translate governance architecture into a clear account of informed, active, and adaptable oversight.
Institutional investor policies connect board accountability with transparent oversight of strategy and material risk. Across the proxy voting policies of at least three of the largest US institutional investors, the recurring questions are practical: Does the board understand the company’s significant risks and opportunities? Are responsibilities clearly allocated? Does the board receive relevant information at an appropriate frequency? Does it challenge management and adapt its approach as strategy and the risk environment change?2 Robust disclosure helps shareholders answer those questions without forcing them to infer the quality of governance from generic statements.
The legal context reinforces the value of disciplined oversight. Under the Caremark line of cases, the threshold for director liability for breach of duty of oversight is high and generally requires particularized allegations of bad faith. But it remains a risk when processes are weak, disregarded, or not prioritized. In recent years Delaware courts have allowed cases to continue to discovery when particularized allegations detailed the board’s inattention to red flags or failure to establish a process for regular reporting or assessment of risks.3 Boards would be wise to maintain processes and records showing active supervision of mission-critical and other material risks. Proxy disclosure is not a substitute for board and committee records, but it can accurately reflect the board’s diligence and signal an established culture of thorough oversight.
1 See EY, Five ways boards can respond to investor expectations on AI (January 2026), https://www.ey.com/content/dam/ey-unified-site/ey-com/en-us/campaigns/board-matters/documents/ey-cbm-five-ways-boards-can-respond-to-investor-expectations-on-ai.pdf
2 BlackRock Investment Stewardship, Proxy Voting Guidelines for Benchmark Policies: U.S. Securities (January 2026), https://www.blackrock.com/gls-download/literature/publication/blackrock-investment-stewardship-benchmark-guidelines-us.pdf; Vanguard Capital Management Investment Stewardship, 2026 Annual Report (September 4, 2026), https://corporate.vanguard.com/content/dam/corp/about-our-funds/pdf/vcm/vcmis_2026_annual_report.pdf; State Street Investment Management, Global Proxy Voting and Engagement Policy (April 2026), https://www.ssga.com/library-content/assets/pdf/global/asset-stewardship/proxy-voting-and-engagement-policy.pdf.
3 Wachtell, Lipton, Rosen & Katz, Risk Management and the Board of Directors (Sept. 2025), https://theliptonarchive.org/wp-content/uploads/Risk-Management-and-the-Board-of-Directors.pdf
Disclosure Pointer 1: Name the Risks— and Explain Why They Matter
Start with specificity. Readers should be able to identify which risks and opportunities are most significant to the company and therefore command board attention. The proxy should align with the company’s other reports; where other disclosure—such as cybersecurity disclosure under Item 106 of Regulation S-K—addresses a risk in detail, the proxy should be consistent with it. Company-specific explanations are more informative than boilerplate: the proxy should explain how material risks connect to company strategy and why they matter now.
The strongest disclosure moves beyond a static inventory. It explains how the enterprise risk-management process identifies and assesses priority risks, which risks rise to the board level, and how that focus changes over time. A description of the company’s enterprise risk-management system provides decision-useful information about how the company identifies, assesses, monitors, and manages the risks that the board oversees.
Core risks may remain stable, while other risks shift with the company’s strategy, operating environment, and emerging technologies. “Spotlights” are useful for disclosing these shifting risks.
The examples below illustrate various approaches to specifying the risks overseen by the board. The common lesson is not to copy a format, but to help readers understand the company’s own hierarchy of risk.
General Dynamics – Discusses which risks rise to board attention in a dynamic environment; lists specific risk topics discussed during the year.


Lockheed Martin – identifies dynamic risks.

Xcel Energy – describes how enterprise risk management program identifies risks and names key risk management areas.

Northrop Grumman – identifies areas of evolving risk; spotlight on evolving AI risk.

Disclosure Pointer 2: Identify the Oversight Owner
Once the key risks are identified, the proxy should make responsibility easy to follow. Explain which matters remain with the full board, which are delegated to committees, and how the board decides between those approaches. Allocation of oversight responsibility should reflect the nature of the risk, the committee’s mandate, and the expertise of its members.
Good disclosure also shows how the structure works as a whole. A committee may have primary responsibility for particular risks, but the full board likely receives the information needed to understand the company’s aggregate exposure and the interaction among risks. Cross-committee reporting, committee-chair updates, and escalation protocols can help demonstrate that delegation does not become fragmentation.
The examples below illustrate how companies clearly communicate the board’s approach to allocating risk oversight responsibilities.
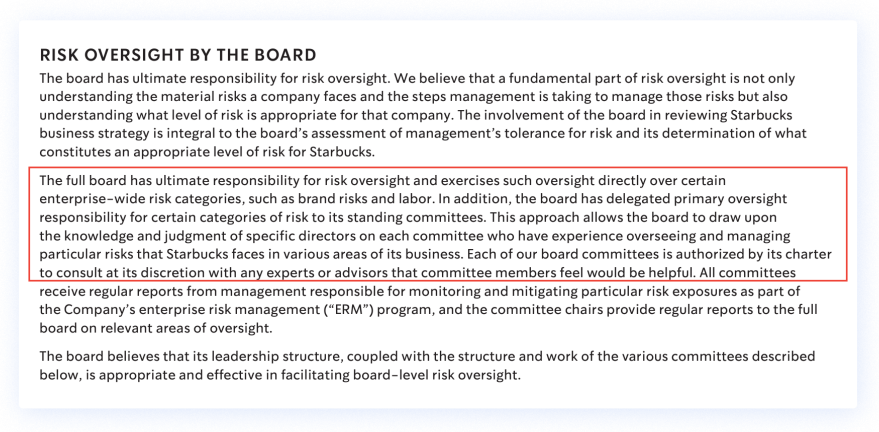
Starbucks – explains how the board delegates risk oversight, based on committee member expertise.
Solventum – specifies which risks are retained by the full board and which are delegated to its committees.

Synchrony – highlights its risk management approach to one of its highest priorities, data protection, including details on Board oversight structure and reporting and noting director expertise.

Xcel Energy – describes how risk is allocated among board and its committees, including dual-responsibility approach for particularly important topics.

Disclosure Pointer 3: Describe the Oversight Process and Activities
Responsibility alone does not establish effective oversight. Shareholders also need to understand what the board or committee actually does. Useful disclosure addresses the rhythm and substance of oversight: how often significant topics appear on agendas; who reports to the board; what information or external advice directors receive; and how directors engage with management.
Activity-based disclosures make the process credible. Show how the board executes its oversight duty. Discussing the frequency and content of information and management reporting to the board is more informative than expressing it only as “regular” reporting. A rapidly changing or high-priority risk may require more frequent discussion, interim updates, dedicated education, or access to outside advisers.
The examples that follow show how information about what the board assesses—including how often and from whom it receives that information—helps stakeholders evaluate the quality of the board’s oversight.
Northrop Grumman – lists specific briefings and reports provided to the board.

Exelon – illustrates how management interacts with the board and identifies key and supporting management participants.

RTX – provides details on content of risk briefings by management.

Allstate – indicates frequency of risk review and identifies from whom reports are received.

General Dynamics – describes briefings and other information received from management and external advisors.

Disclosure Pointer 4: Show the Board’s Capabilities and Readiness
The final step is to connect oversight responsibilities with the people performing them. A clear chain should be visible: a committee oversees a particular risk; its members collectively possess relevant skills; director biographies explain the experience behind those skills; and the board supplements existing knowledge through continuing education, external advice, and thoughtful refreshment.
Skills matrices are most useful when the skill definitions are specific enough to be meaningful and when they evolve with the company’s needs. Similarly, biographies are most useful when they show not just that a director has a particular risk expertise, but instead shows how their experience supports oversight of the company’s particular exposures. Where refreshment has added capabilities tied to strategic priorities or emerging risks, say so. The same is true of continuing education: identify the subjects addressed and how the program helps directors remain current.
The examples that follow show several ways to make the important connection between oversight and director skills, pulling from sections of the proxy statement beyond risk oversight. The objective is to demonstrate present capability while showing that the board is preparing for what comes next.
Allstate – specifies board training on AI; indicates topics for which board engaged outside experts and advisors.

Allstate – ties director expertise to effective committee oversight.

Walmart – shows committee’s expertise supporting effective oversight.

Equifax – describes how directors build practical fluency in AI.

Comprehensive example: Fortive
Companies preparing the next proxy should test their draft against four questions investors are asking: Can a shareholder tell which risks receive board attention, and why? Is it clear who owns oversight? Does the disclosure reveal what the board actually does? And can the reader understand why the directors have the necessary expertise and readiness? In its 2026 proxy statement (pages 17–21), Fortive comprehensively addresses all of these questions, providing disclosure that is decision-useful—and reflects the quality of oversight the board intends to provide.
Numerical references are to the pointers discussed above.


